Foreign Pension Tax in Thailand: Treaties and Remittance
A pension is employment income under section 40(1). A resident in Thailand 180 days or more who brings in a pension earned from 2024 includes it in Thai tax. Treaties differ: Australia and the US leave a private pension to the state of residence. Canada leaves it to the state where it arises.
On this page
A pension payment lands in a Thai bank account. Two facts decide whether Thai tax follows. The pension must have arisen on or after 1 January 2024. You must also have been resident in the year it arose.
Is a foreign pension taxed in Thailand?
Section 40(1) of the Revenue Code lists pensions among employment income. The Revenue Department applies the remittance rule to foreign income under section 40(1) to (8).
Who counts as resident
The Revenue Department defines a person in Thailand as someone in Thailand a total of 180 days or more between 1 January and 31 December. Someone in Thailand 179 days is not a resident for that year. A person in Thailand fewer than 180 days is not taxed on foreign income of that year, even if it is brought into Thailand.
Which pension payments the 2024 rule reaches
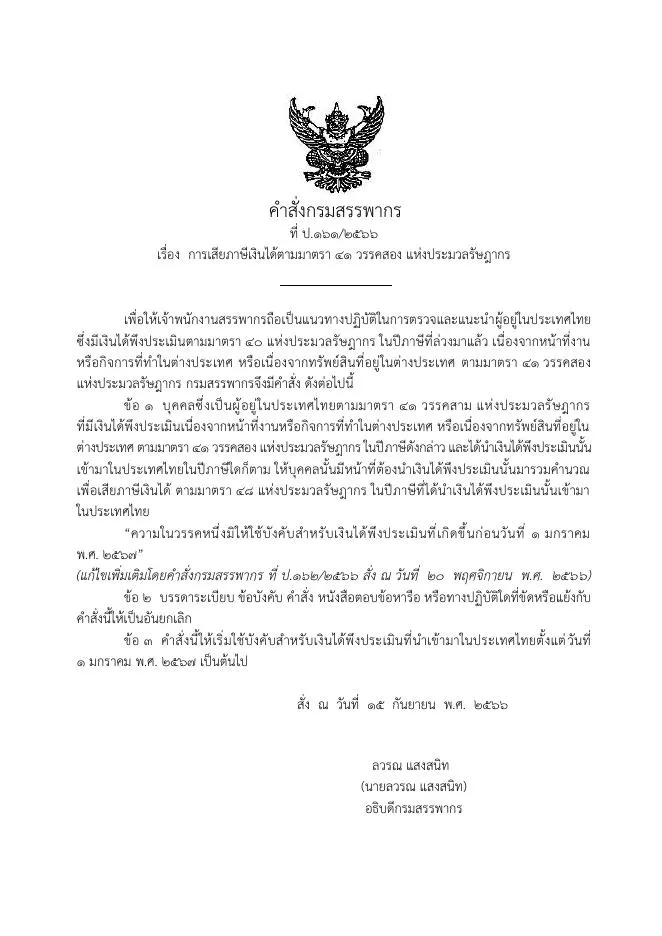
Order Por. 161/2566 says a resident who brings foreign-source income into Thailand in any tax year includes it in that year’s tax computation. The order applies to income brought in from 1 January 2024.
- A pension earned from 2024, in a year you were resident, is taxed when you bring it in that year or later.
- Income that arose before 1 January 2024 is not taxed when brought in, even in 2024 or later.
- In the Revenue Department example, bank interest that arose before 1 January 2024 is not taxed when brought in later.
- Savings built abroad in years you were in Thailand fewer than 180 days can come in without tax.
- The principal of a foreign deposit is not taxed, but its interest is.
- Convert foreign income at the rate on the day it is brought into Thailand.
For the full residency test and examples, see Thailand tax residency and foreign income.
What the treaties say about pensions
Treaty articles differ, so each country below follows the Revenue Department’s published text. Where a treaty and the Revenue Code differ, the rate more beneficial to the taxpayer applies. Treaties use credit and exemption methods.
| Country | Private pension | Article |
|---|---|---|
| Australia | Taxable only in the state of residence | 18 |
| Canada | Taxable only in the state where it arises | XVIII |
| Denmark | May be taxed in both states | 18 |
| France | The state where it arises may tax it | 18 |
| Germany | The other state taxes it only as an enterprise expense there | 18 |
| Korea | The state where it arises may tax it | 18 |
| Netherlands | Taxable only in the state of residence, with an enterprise-profit exception | 18 |
| New Zealand | Taxable only in the state of residence | 19 |
| Norway | The state of residence has the sole taxing right | note |
| Switzerland | Taxable only in the state of residence | 17 |
| United Kingdom | No article on private or state pensions | none |
| United States | Taxable only in the state of residence | 20 |
For a Thai resident, “state of residence” means Thailand. “Where it arises” means the pension’s home country.
United States
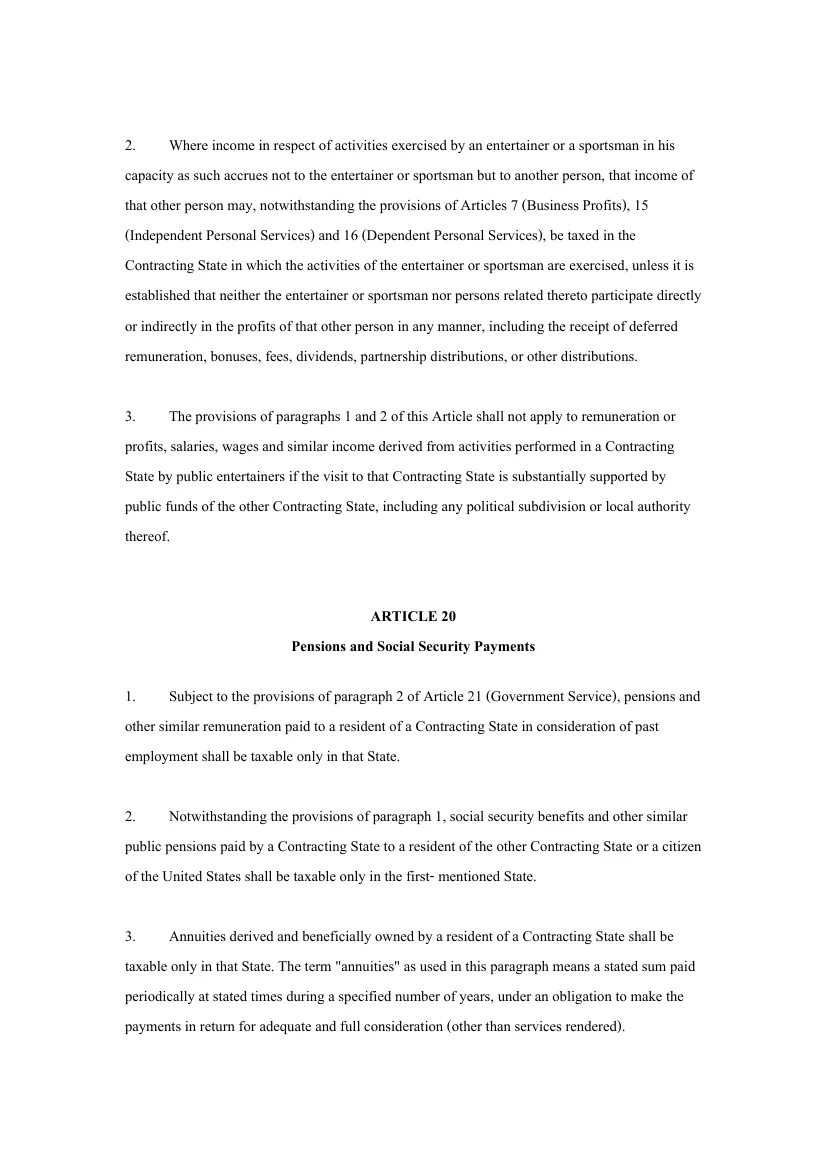
Article 20 paragraph 1 of the Thailand-US convention says pensions and similar remuneration paid to a resident of one state for past employment are taxable only in that state.
pensions and other similar remuneration paid to a resident of a Contracting State in consideration of past employment shall be taxable only in that State.
Thailand-US convention, Article 20 paragraph 1, Revenue Department English text
Social security benefits and similar public pensions paid by one state to a resident of the other state, or to a US citizen, are taxable only in the paying state. The citizenship rule in Article 1 does not affect Article 20 paragraphs 2 and 5.
The convention lets each state tax its residents and, by reason of citizenship, its citizens as if the convention had not come into effect. For a US citizen in Thailand, that rule keeps the US taxing right over a private pension, because the exceptions name only Article 20 paragraphs 2 and 5. Social security keeps the paying-state-only rule.
Australia
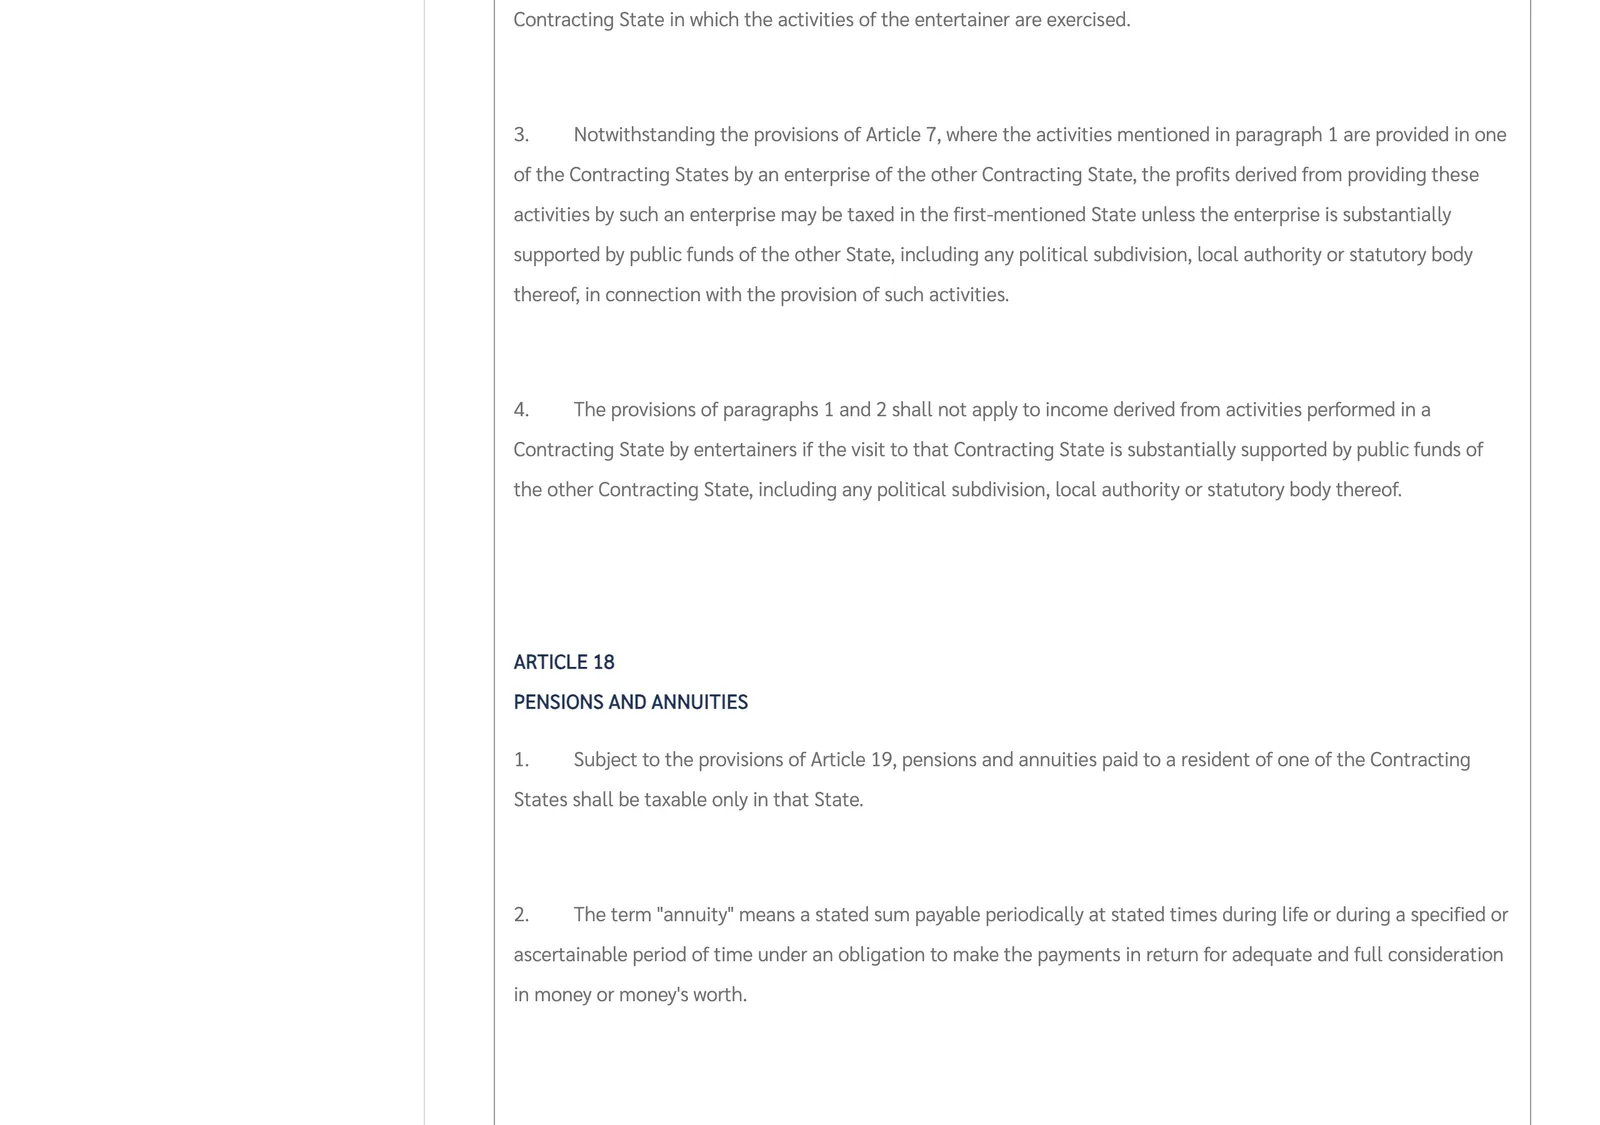
Subject to the provisions of Article 19, pensions and annuities paid to a resident of one of the Contracting States shall be taxable only in that State.
Thailand-Australia convention, Article 18 paragraph 1, Revenue Department English text
In the Norway convention the state of residence has the sole taxing right, so a Norwegian pensioner resident in Thailand is taxable only in Thailand.
Germany
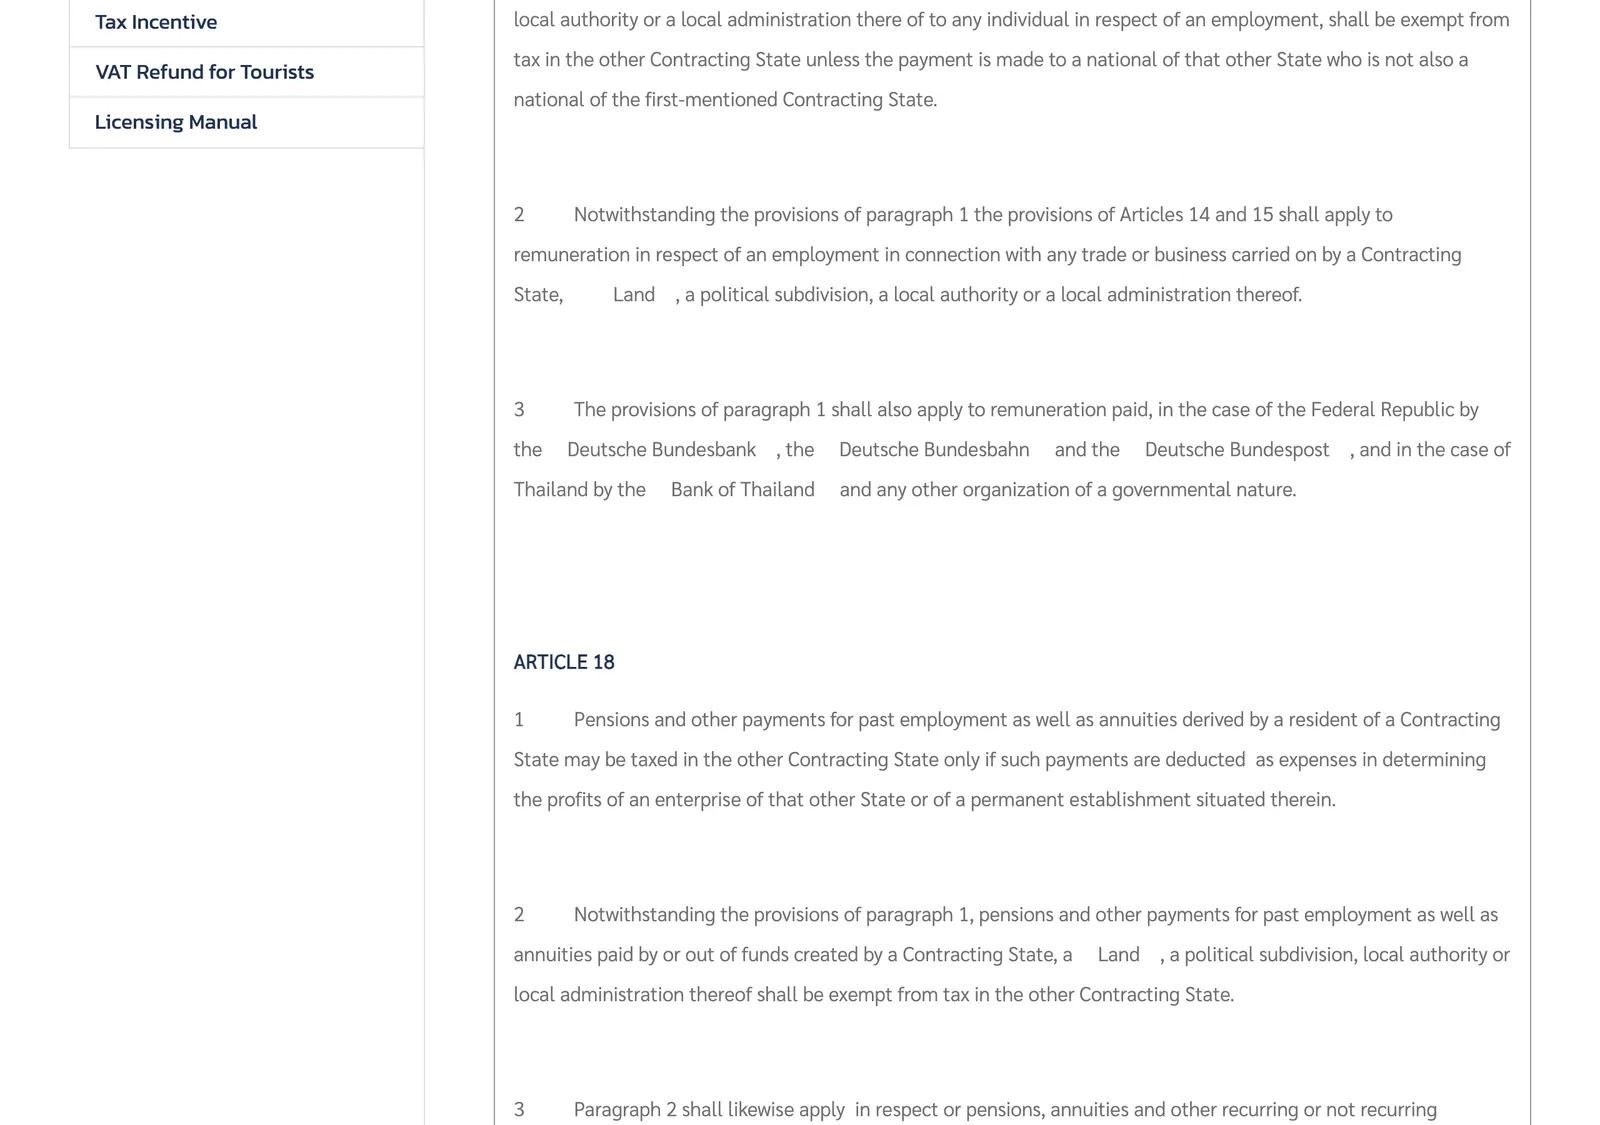
In the Thailand-Germany agreement, pensions and annuities derived by a resident of one state may be taxed in the other state only in one case. The case is a deduction as expenses of an enterprise or permanent establishment there. Pensions and annuities paid by a state, a Land or a local authority are exempt from tax in the other state.
United Kingdom
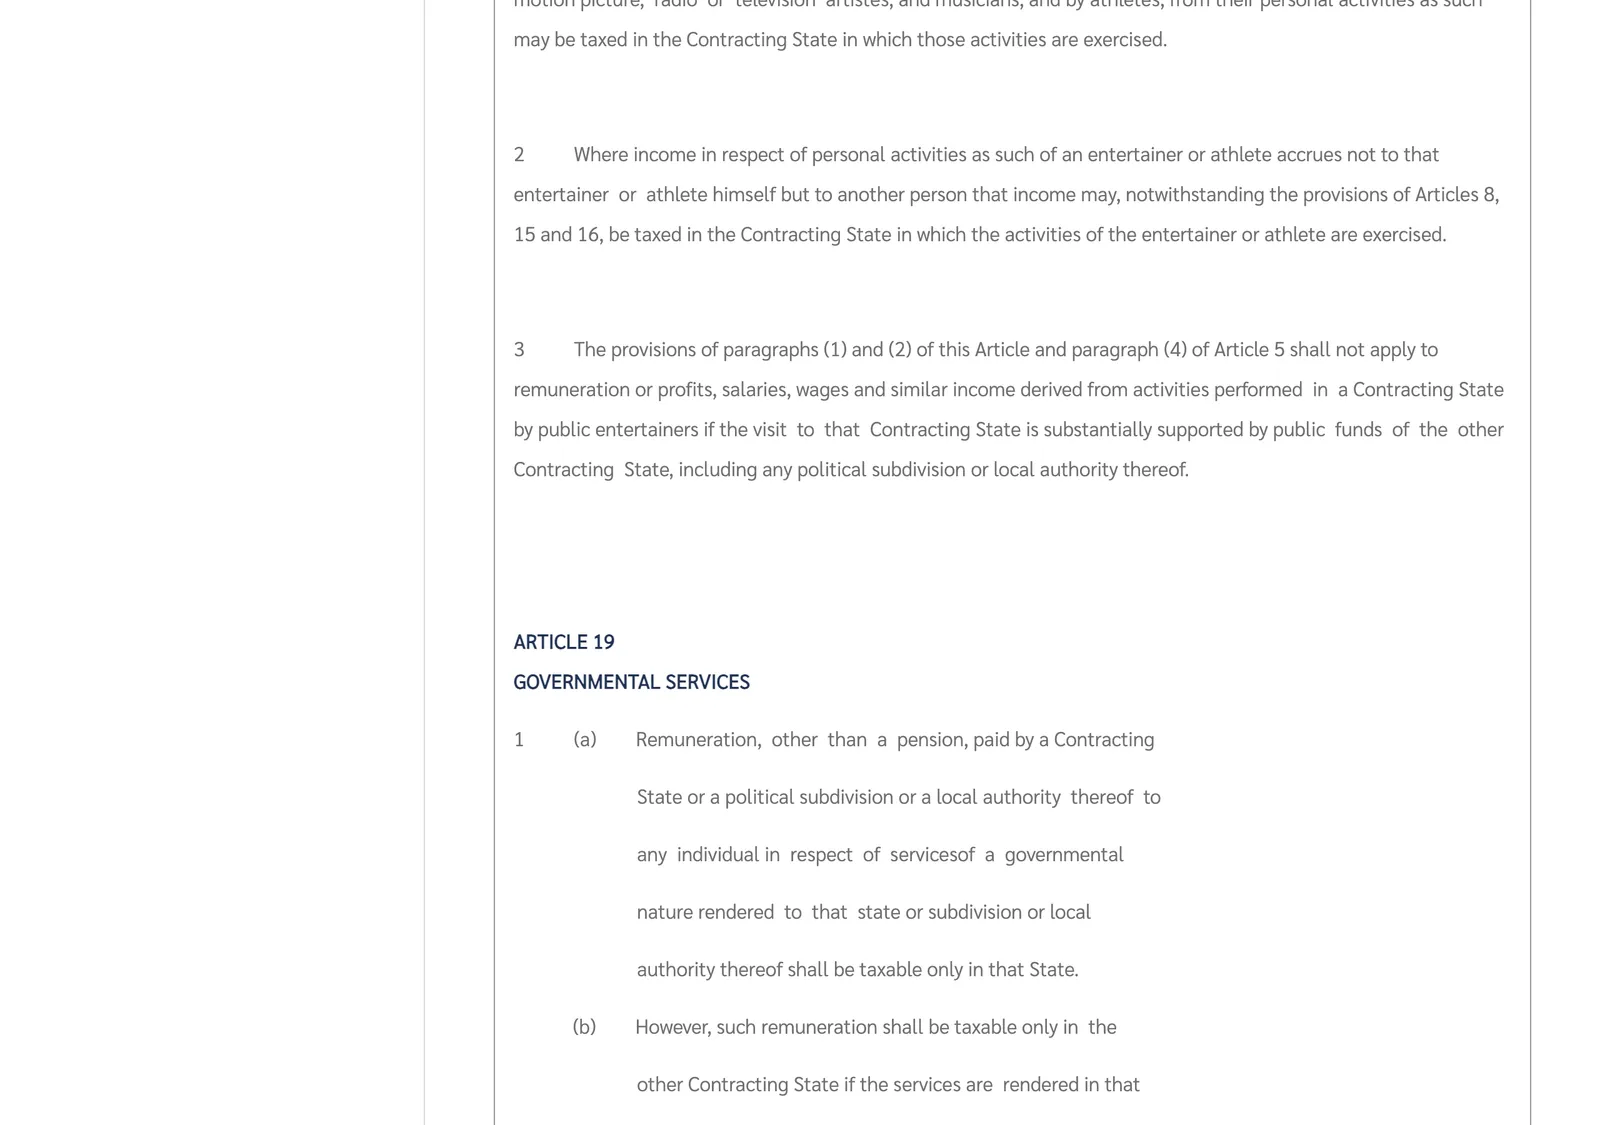
The Thailand-UK convention has no article on private or state pensions. A pension paid for government service is taxable only in the paying state, unless the recipient is a national and resident of the other state. For other UK pensions, the Thai rules on this page apply.
Government pensions
A pension paid by a state for government service follows its own article. Under the US convention it is taxable only in the paying state, unless the recipient is a resident and national of the other state. The Australia convention has the same pattern.
Other treaty countries
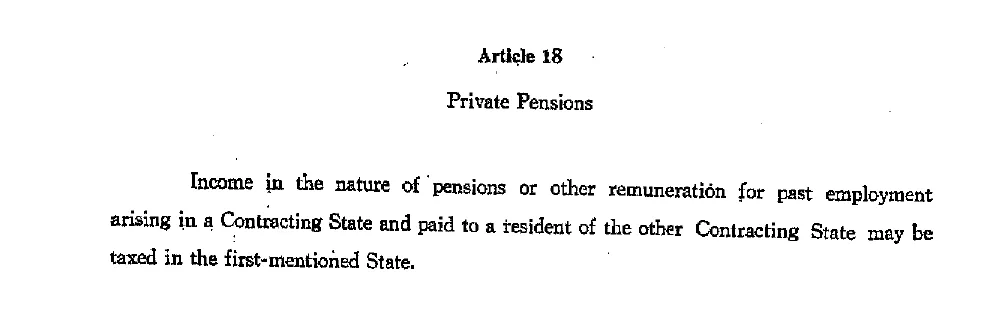
- Canada: pensions for past employment arising in one state and paid to a resident of the other are taxable only in the state where they arise.
- France: the state where the pension arises may tax it.
- Netherlands: pensions and annuities are taxable only in the state of residence. The other state may tax income charged against profits of an enterprise there.
- Switzerland: pensions for past employment are taxable only in the state of residence.
- New Zealand: pensions, government pensions included, and annuities are taxable only in the state of residence.
- Korea: the state where the pension arises may tax it.
- Denmark: pensions, social security payments and annuities may be taxed in both states.
Residence certificate
A Norwegian pensioner gives the Norwegian tax authority a Certificate of Residence issued by the Thai Revenue Department. Other treaty countries set their own procedure, and the Thai side is the same.
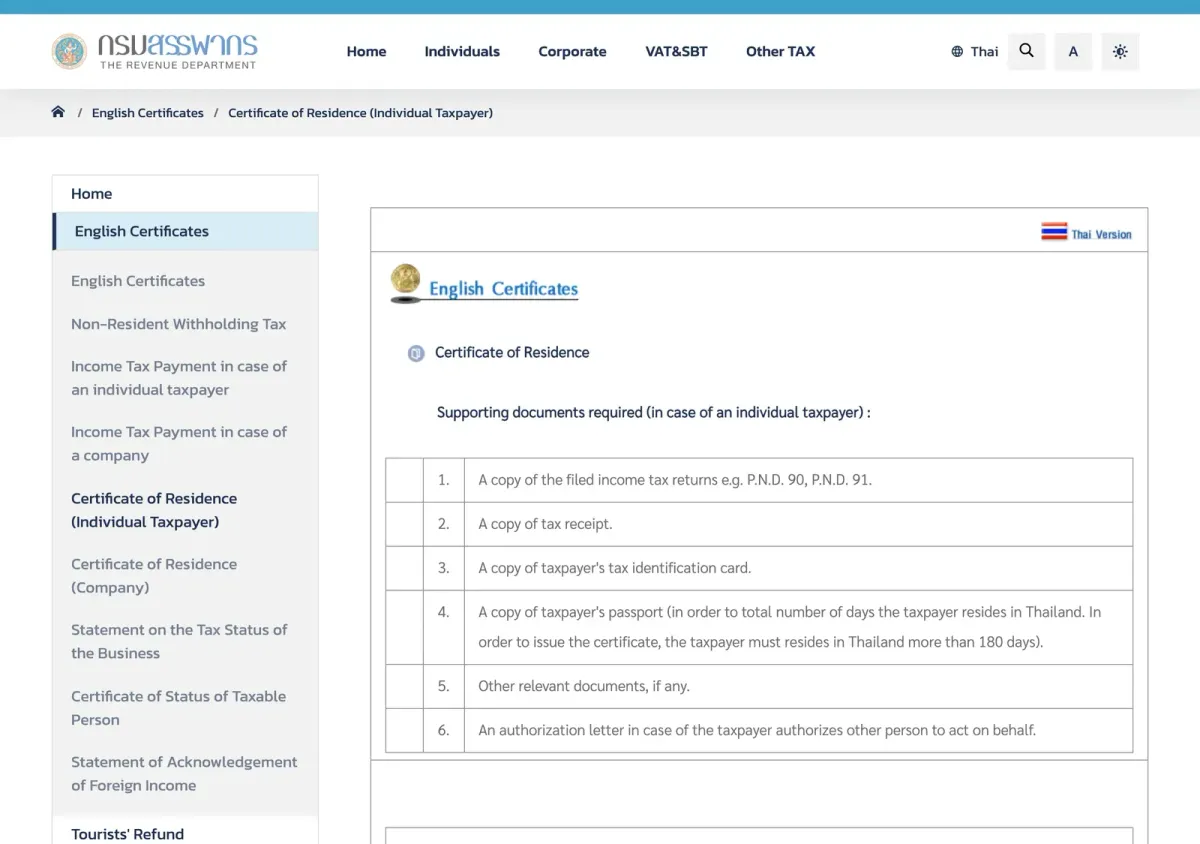
Supply a copy of the filed PND 90 or PND 91, the tax receipt and the taxpayer ID card. Add a passport copy that shows the days in Thailand. The taxpayer must reside in Thailand more than 180 days.
LTR Wealthy Pensioner visa
The foreign income exemption applies to three LTR categories, including Wealthy Pensioners. The LTR Wealthy Pensioner category is for retirees aged 50 and older with an annual pension or stable passive income.
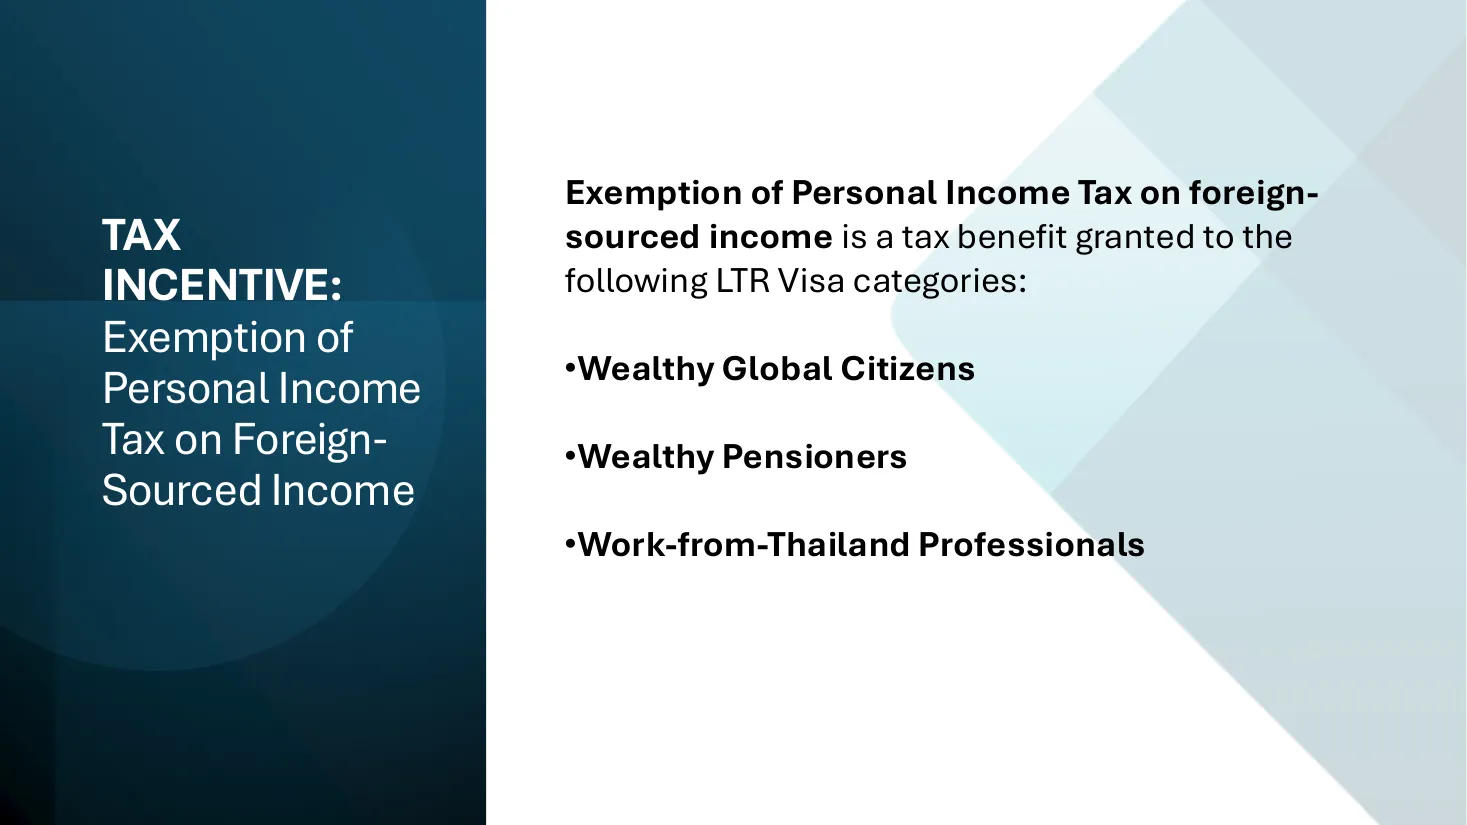
Wealthy Pensioners need passive income of at least USD 80,000 a year when they apply, and salary does not count. The retirement visa routes are in Thailand retirement visa: Non-O, O-A and O-X.
Tax ID, return and deadlines
A foreigner with no personal identification number must apply for a taxpayer identification number. The application is due within 60 days of the date the person derives assessable income, on Form L.P. 10.1. A foreigner present for one period of up to 14 days and up to 90 days in total in a tax year does not need to apply.
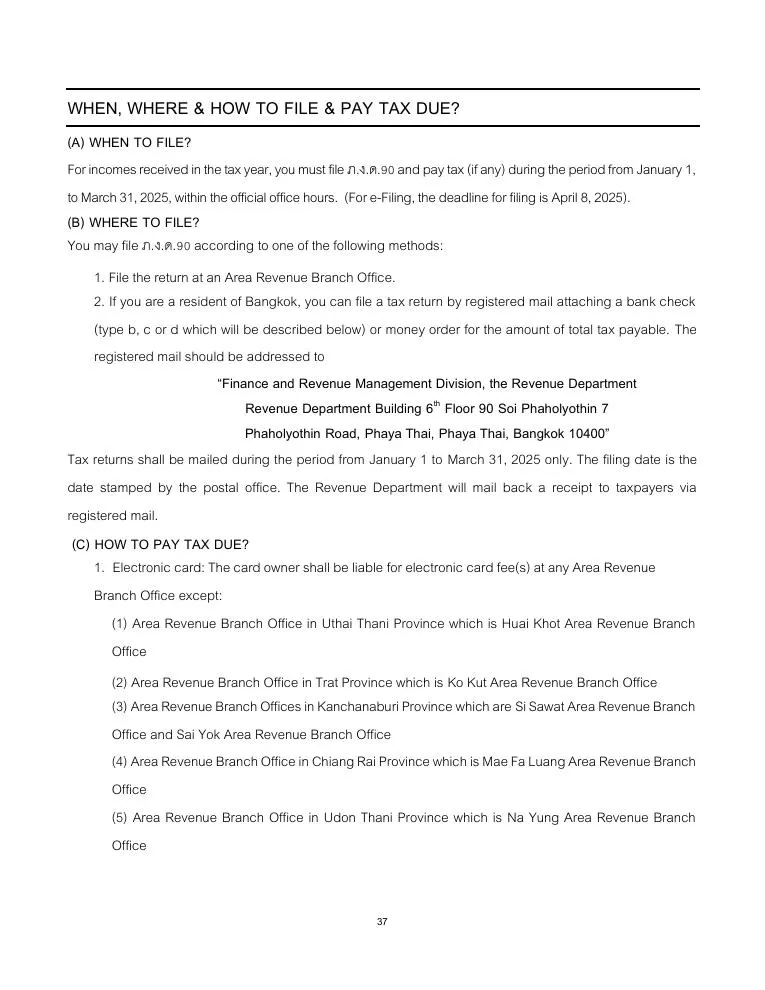
- PND 90 is the general return, and someone with employment income only uses PND 91.
- For tax year 2025, paper filing ran from 1 January to 31 March 2026, and e-Filing until 8 April 2026. Dates for tax year 2026 are not announced yet.
- Late payment brings a surcharge of 1.5% per month, and a fine of up to 2,000 baht may also be charged.
- Tax of 3,000 baht or more may be paid in 3 equal instalments.
- The first THB 150,000 of net income is exempt.
- For employment income the guide lets a taxpayer deduct expenses equal to 50% of the income, up to 100,000 baht.
- A taxpayer aged 65 or older attaches the Income Exemption Entitlement Form for income exemption up to 190,000 baht.
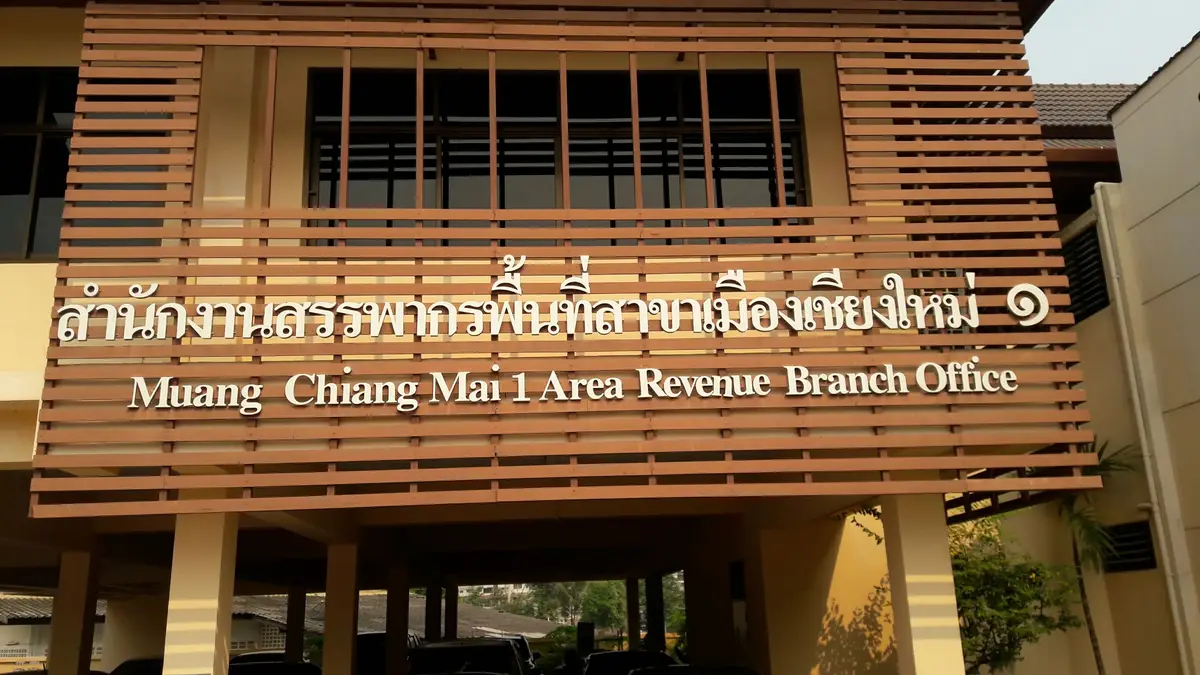
The Chiang Mai Area Revenue Branch Office 1-2 is at 2 4 Charoen Prathet Rd, Tambon Chang Khlan. Its telephone number is +66 53 284 172.
2 4 Charoen Prathet Rd, Tambon Chang Khlan, Mueang Chiang Mai District, Chiang Mai 50100, Thailand · Open in Google Maps (opens in a new tab)
Photo credits
- Photos and clips uploaded to Google Maps (Chiang Mai Area Revenue Branch Office 1-2 on Google Maps (opens in a new tab)) by Chai TNK.
Not confirmed: How a Thai return treats a pension that a treaty leaves to the other state is not published. Tax year 2026 filing dates are not announced yet.
Reach readers planning life in Chiang Mai. Advertise → hello@chiangmaijao.com
Common questions
Is my foreign pension taxable in Thailand?
Section 40(1) lists pensions among employment income. A resident who brings foreign-source income earned from 2024 into Thailand includes it in Thai tax.
Is a pension paid before 2024 taxed when I bring it in?
Income that arose before 1 January 2024 is not taxed when brought in, even in 2024 or later. Interest on a foreign deposit is assessable income when brought in.
Is US Social Security taxed in Thailand?
Under Article 20 paragraph 2 of the Thailand-US convention, social security benefits paid by the United States to a Thai resident are taxable only in the paying state. The citizenship rule does not affect that paragraph.
Does the treaty with Australia exempt my pension?
The convention says pensions and annuities paid to a resident of one state are taxable only in that state, subject to Article 19.
What do the Canada, France, UK and Dutch treaties say about my pension?
Canada: taxable only in the state where the pension arises. France: the state where it arises may tax it. The Netherlands: taxable only in the state of residence. The UK convention has no article on private or state pensions.
How do I get a Thai Certificate of Residence?
Supply the filed PND 90 or PND 91, the tax receipt, the taxpayer ID card and a passport copy. The taxpayer must reside in Thailand more than 180 days.
How does the German agreement treat pensions?
Pensions derived by a resident of one state may be taxed in the other state only if deducted as expenses of an enterprise or permanent establishment there. State and Land pensions are exempt in the other state.
Are government pensions treated differently?
Under the US convention, a pension for government service is taxable only in the paying state, unless the recipient is a resident and national of the other state. The Australia and UK conventions have the same pattern.
Do I file PND 90 or PND 91?
PND 90 is the general return, and someone with income from employment only uses PND 91. Pensions are listed with employment income.
When is the return due?
For tax year 2025 paper filing ran from 1 January to 31 March 2026, and e-Filing until 8 April 2026.
Read next
General information checked against the sources listed above, not legal advice for your situation. Rules and office practice change; confirm with the immigration office or a licensed adviser before you act. See how guides are checked.
Spotted an error? Report it.